辽宁大学经济学前沿高端讲座
Stability of a Heterogeneous Agent Model with Precautionary Savings
主讲人:朱胜豪 教授(对外经济贸易大学)
主持人:余莉 助理教授(辽宁大学李安民经济研究院)
嘉宾介绍:王丹丹 助理教授(辽宁大学李安民经济研究院)
时间:2026年10月9日(周五) 10:30-12:00(北京时间)
地点:辽宁大学蒲河校区经济学部大楼483会议室
语言:中文/英文
摘要:The continuous-time heterogeneous-agent formulated by Achdou–Han–Lasry–Lions–Moll (2022) turns an individual Hamilton–Jacobi equation and a population Kolmogorov equation into a backward–forward PDE system. The individual wealth accumulation under the Macro general equilibrium follows a McKean-Valsov stochastic differential equation. We find that the wealth distribution converges to a stationary distribution within a ball characterized by the relative entropy. We establish the local stability of the macroeconomy modeled as a nonlinear particle system. Finally, leveraging the relationship between Dirichlet forms and KL divergence, we investigate the stability of heterogeneous macroeconomic models via functional inequality techniques.
主讲人简介:
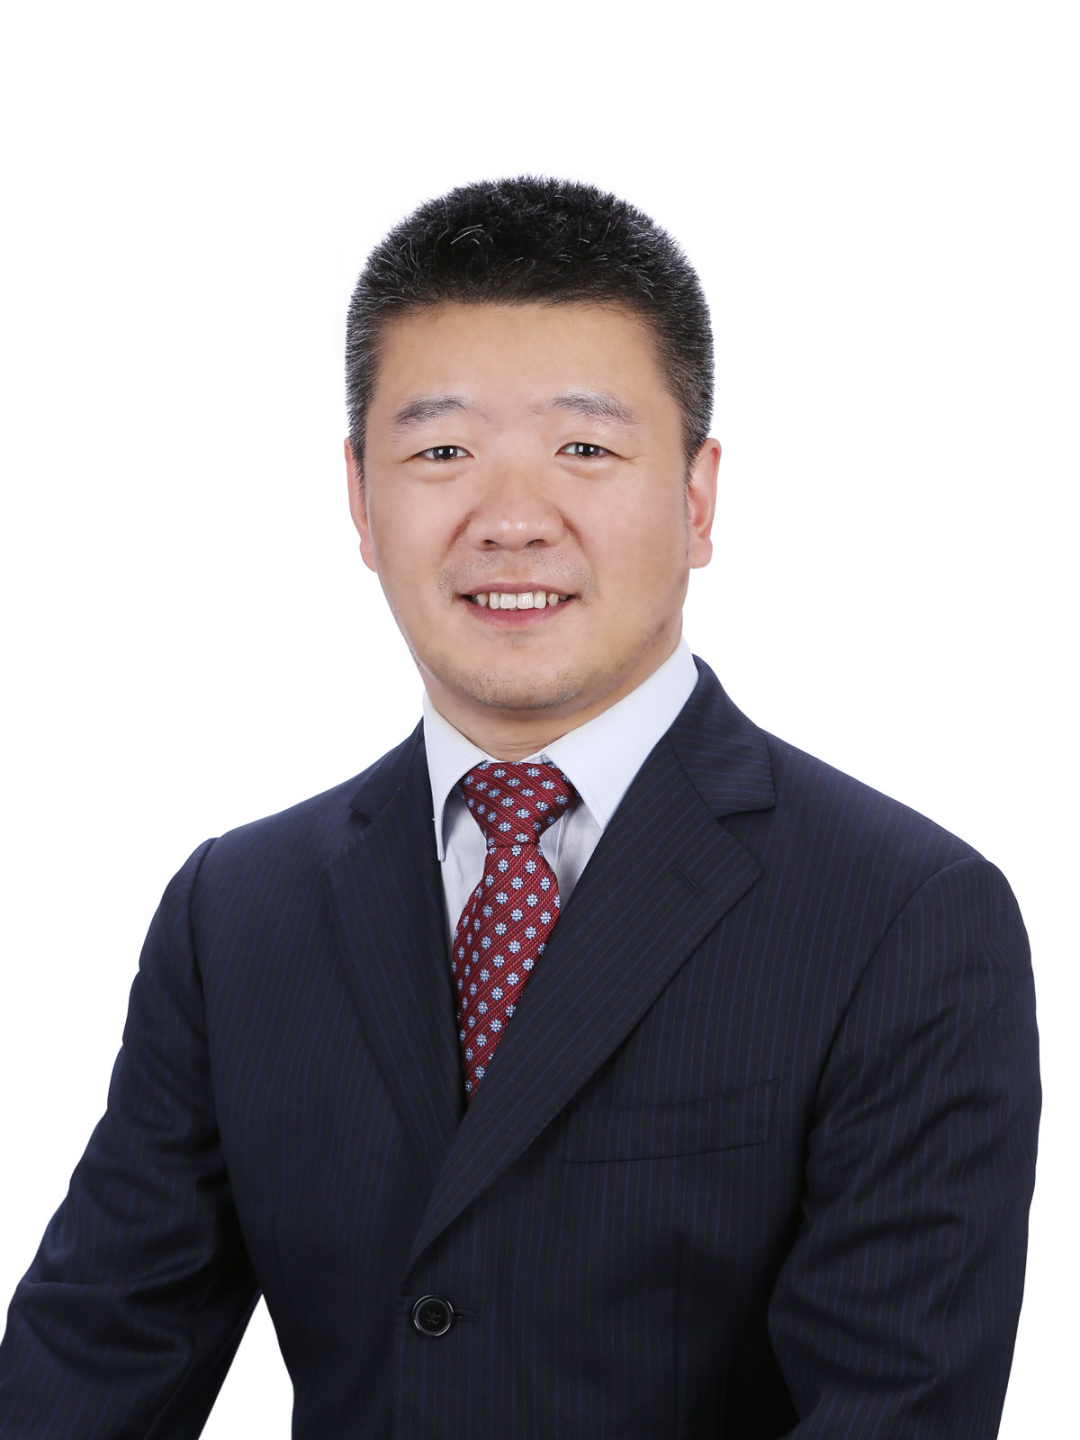
朱胜豪,现任对外经济贸易大学教授。纽约大学经济学博士。在Econometrica, Journal of Economic Theory, International Economic Review等国际一流经济学期刊上发表数篇论文。学术成果在Google Scholar上被国际同行引用1200多次。朱胜豪教授的主要研究领域是宏观经济和收入分配。他的研究结合动态宏观经济学异质性模型和家庭微观大数据,利用计算技术解决微观主体决策的激励相容问题。正在主持一项国家自然科学基金原创探索计划项目。
辽宁大学经济学前沿高端讲座
Optimal Pricing with Dynamic In-Consumption Social Interactions
主讲人:沈吉 副教授(北京大学光华管理学院)
主持人:熊泽源 助理教授(辽宁大学中国经济研究院)
嘉宾介绍:何超 副教授(辽宁大学中国经济研究院)
时间:2026年10月9日(周五) 14:30-16:00(北京时间)
地点:辽宁大学蒲河校区经济学部大楼547会议室
语言:中文/英文
摘要:Social interaction is now often part of the consumption of digital products: in online games, fitness apps, and live streams, users interact while they consume, and interaction enhances or dampens a user’s enjoyment depending on whom she encounters. The firm that sells such a product prices something whose value its own users shape. We ask how the firm should price when the price selects not only who participates but whom every participant meets. In a dynamic model with forward-looking consumers, we characterize the stationary equilibrium and compare participation, the elasticity of demand, profit, and the optimal price with a no-interaction benchmark. In the main model, where a consumer’s willingness to pay and her value as a partner are aligned, interaction never lowers the firm’s profit and raises it whenever upward influence exists, even when downward influence dominates; for weak interaction, whether the optimal price falls depends on the distribution of consumer valuations rather than on the direction of influence. In an extension in which willingness to pay and value as a partner are separate characteristics, the price can drive out the very users who make interaction valuable, and interaction can lower profit. We show that whether interaction raises the firm’s profit is decided not only by how positive it is but, more importantly, by whom the price keeps.
主讲人简介:
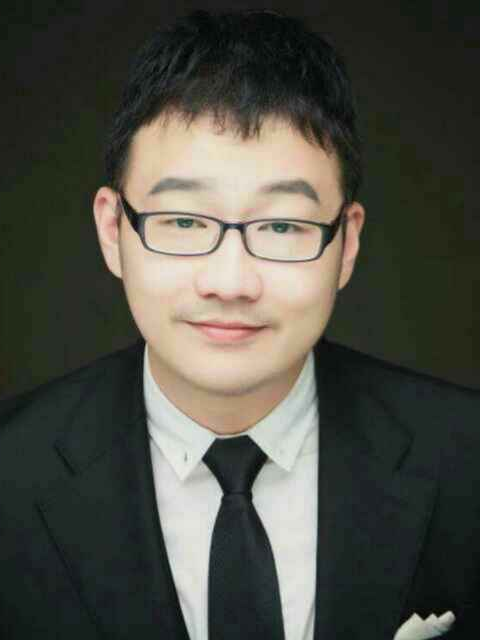
沈吉,在伦敦政治经济学院获得金融学博士学位,现任教于北京大学光华管理学院。研究兴趣主要在资产定价理论,数字经济等。论文发表散见于《经济研究》《世界经济》《金融研究》和Review of Financial Studies,Management Science,Journal of Banking and Finance等国内外学术期刊。
崇山校区:沈阳市皇姑区崇山中路66号 邮编:110036
蒲河校区:沈阳市沈北新区道义南大街58号 邮编:110136
武圣校区:辽阳市白塔区青年大街38号 邮编:111000
联系方式:024-62202013
中国沈阳 辽宁 大学 Copyright by 辽宁大学 2016 辽ICP备05001361号
崇山校区:沈阳市皇姑区崇山中路66号
邮编:110036
蒲河校区:沈阳市沈北新区道义南大街58号
邮编:110136
武圣校区:辽阳市白塔区青年大街38号
邮编:111000
联系方式:024-62202013
中国沈阳 辽宁大学 辽ICP备05001361号